A Massachusetts court just handed down a homeowners claim decision that every Greater Boston homeowner should know about, not because of how it ended, but because of how it started.
In a ruling dated September 21, 2026, a Suffolk Superior Court judge found that PURE, a high-value home insurer, willfully violated two provisions of the Massachusetts unfair claim settlement law while handling a fire claim on a historic home in Great Barrington. The insurer’s first rebuild estimate came in at about $5 million. A three-person reference panel later set the actual reconstruction cost at about $11.5 million. The homeowners still recovered nothing extra in court, because they could not prove damages caused by the violations.
Most claims are far smaller, but the lessons apply to a triple-decker in Dorchester as much as an estate in the Berkshires.
What happened in the PURE case
The fire hit on December 29, 2020. The house was built in 1905, largely of American chestnut, with maple floors, hand-built stone chimneys, and a stone foundation. Early on, a contractor at the site estimated reconstruction at $12 million to $16 million.
A little over a month later, the insurer’s formal estimate came in at about $5.028 million. According to the court, that estimate priced the maple floors as oak, used prefabricated fireplaces instead of stone, left out the cost of roughly 51 windows and 60 doors, and assumed the house was about 7,000 square feet when it was closer to 9,200.
The homeowners hired their own construction professionals, and the dispute went to statutory reference, the Massachusetts process for fire claims when the two sides disagree on the amount of loss. The panel set the dwelling loss at $11,502,332.84. In total, the insurer ended up paying about $16 million across dwelling, contents, and additional living expenses.
The judge found the insurer failed to make a prompt, fair settlement once liability was reasonably clear, and compelled the homeowners to go to litigation by offering substantially less than they ultimately recovered. Even so, judgment entered for the insurer on the unfair practices claims because the homeowners did not prove separate damages from those violations. The ruling can still be appealed.
Why this matters right now
Claim handling is getting national attention. On October 2, 2026, Senators Elizabeth Warren and Josh Hawley sent letters to six large home and auto insurers asking for data on claims closed without payment and on changes to claim handling over the past decade.
And heating season is starting. A fire or burst pipe in January is when you find out what your policy and your paperwork are worth.
Your rights under Massachusetts law
Massachusetts General Laws Chapter 176D, Section 3(9) lists unfair claim settlement practices. They include refusing to pay without a reasonable investigation, failing to make prompt, fair settlements once liability is reasonably clear, and failing to promptly explain the policy basis for a denial or compromise offer.
For fire losses, Chapter 175, Section 99 sets out the standard fire policy, including the reference process. If you and the company cannot agree on the amount of loss, each side picks a referee and those two pick a third. A written award signed by a majority is binding on the amount. The same section generally gives you two years from the date of loss to file suit, with some extensions when a reference is underway.
The Massachusetts Division of Insurance also takes consumer complaints. Contact your agent and the company first. The Division cannot give legal advice or value a claim. For a serious dispute, talk to a Massachusetts attorney.
How to protect yourself before and after a claim
-
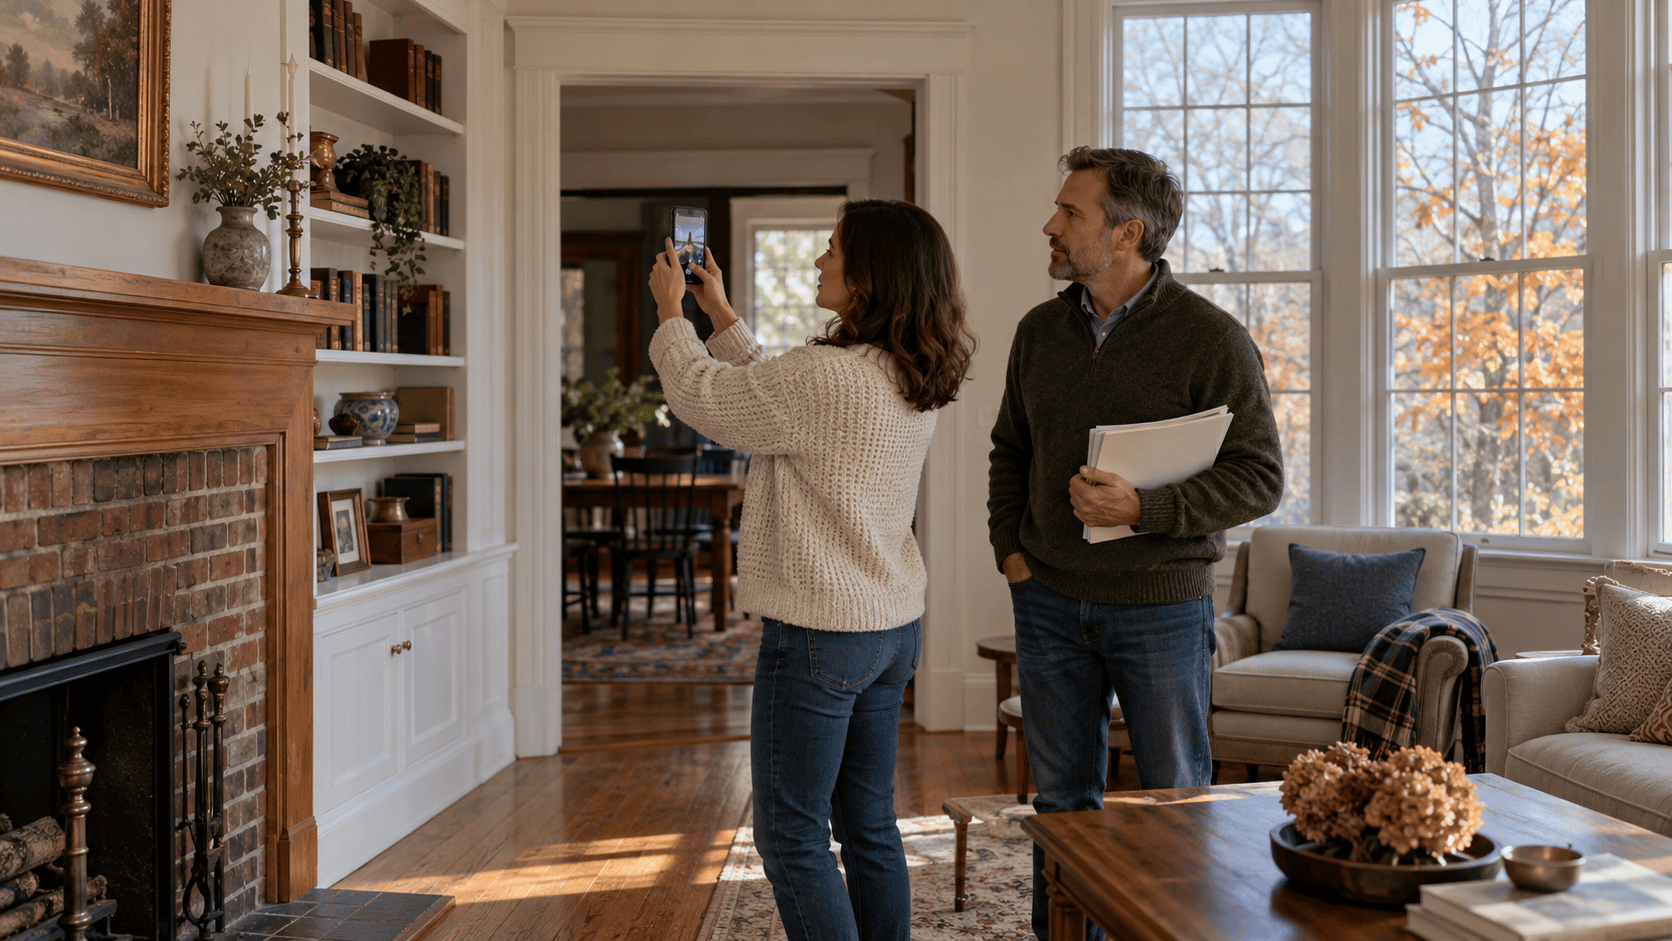
Document your home before anything happens. Walk every room with your phone and record finishes, built-ins, windows, and doors. In the PURE case, the gap between the first estimate and the final number came down to materials and square footage.
-
Keep records of improvements. The Division of Insurance recommends giving the adjuster records of improvements you have made.
-
Report promptly and protect the property. Your policy may set a notice deadline and may require temporary repairs to prevent further damage. Keep every receipt.
-
Do not make permanent repairs before inspection. The Division of Insurance warns that a company may deny a claim if permanent repairs are made before it inspects.
-
Put everything in writing. Keep copies of all correspondence. For calls and meetings, note the date, the person’s name and title, and what was said.
-
Ask for the basis. If an offer seems low or a claim is denied, ask for an itemized explanation citing the policy language. If the numbers do not match your house, get your own contractor estimate.
-
Check your dwelling limit today. Your coverage should reflect what it would actually cost to rebuild your home with like kind and quality materials, not what you paid for it.
The best time to fix a claim is before it happens
Most claim fights start with a gap: a dwelling limit that has not kept up with construction costs, a policy that does not match the house, or missing records. Those are much easier to fix before a loss.
Send us your current homeowners or condo declarations page and we will review your dwelling limit, your replacement cost terms, and what your policy may or may not cover for a home like yours.