On September 30, 2026, a Lowell staffing agency owner was sentenced to 13 months in federal prison for hiding more than $6.2 million in payroll. According to federal prosecutors, he paid temporary workers mostly in cash from 2016 to 2023, dodged more than $1.5 million in payroll taxes, and used the false payroll numbers to buy workers’ comp insurance at lower premiums. The Insurance Fraud Bureau of Massachusetts helped investigate. He now owes $1,652,573 in restitution.
That is an extreme case. But the mechanism behind it, the gap between the payroll you estimate and the payroll you actually pay, shows up in honest Greater Boston businesses every year. It shows up as a workers’ comp premium audit, and sometimes as a bill nobody planned for.
How Massachusetts Workers’ Comp Premium Is Built
Your workers’ comp premium is not a flat fee. Under the Massachusetts workers’ compensation manual published by the Workers’ Compensation Rating and Inspection Bureau (WCRIB), premium is based on the remuneration you pay for employees’ services, multiplied by a rate per $100 of payroll for each classification code on your policy.
At the start of the policy, that payroll is an estimate. After the policy period ends, the carrier audits your actual records and calculates your final earned premium. If you paid more payroll than you estimated, or paid it in a higher-rated class, you owe the difference. If you paid less, you may get money back.
The rates themselves are also in the news. In July 2026, the Supreme Judicial Court sent the Commissioner of Insurance’s 14.6% workers’ comp rate cut from 2024 back for a fuller explanation, while agreeing the Commissioner had the authority to reject the rates the WCRIB proposed. Rate levels can move. Your audit is the part you control.
Where Honest Businesses Get Surprised
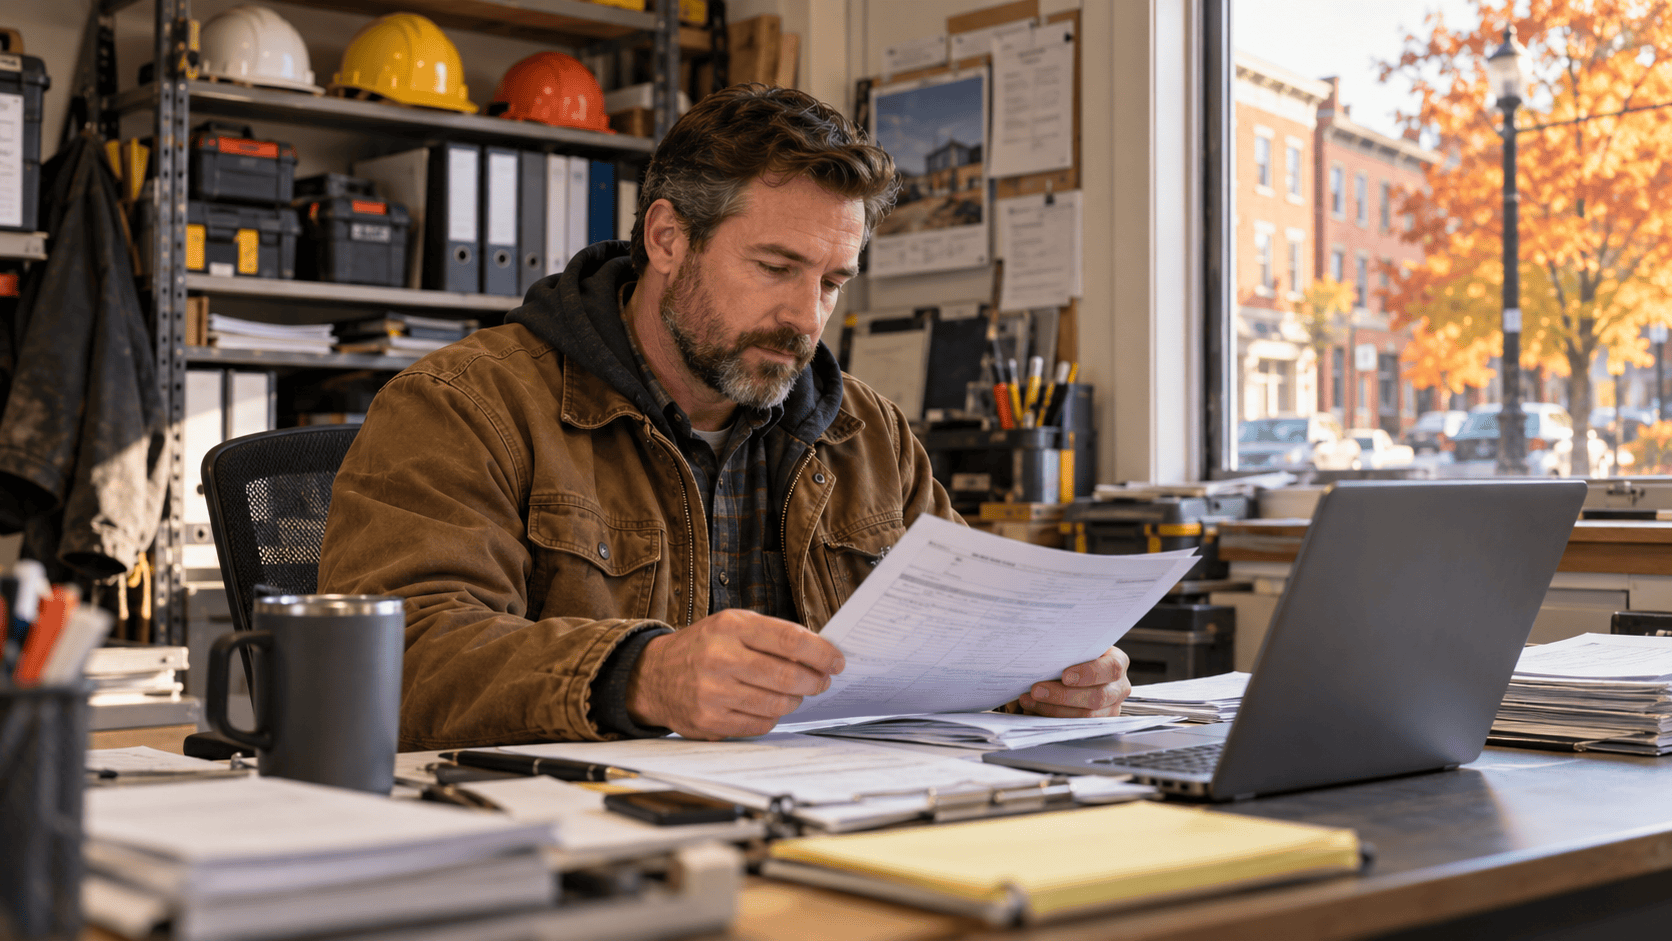
Most audit surprises are not fraud. They are paperwork. A contractor in Quincy hires extra help for a busy summer. A restaurant in Somerville adds a catering crew. A cleaning company in Framingham brings on a few “independent” subs. Nobody updates the estimate, and nobody collects the right documents.
The biggest trap is uninsured subcontractors. Under the Massachusetts manual, if a subcontractor does work for you and you cannot show they carry their own workers’ comp coverage, their payroll can be added to your premium at audit. The Massachusetts Division of Insurance has described this exact review in a past audit appeal: the audit looks at whether additional premium is due for people who work for you as subcontractors or independent contractors but are not covered under their own policies.
Calling someone a 1099 contractor does not settle the question. Massachusetts uses a strict three-part test for independent contractors under its wage laws, and workers’ comp has its own definition of “employee.” The Supreme Judicial Court said in Camargo’s Case (2018) that the wage-law test does not replace the workers’ comp definition. Either way, the safest move is the same: get proof of coverage from anyone you pay to do work in your line of business.
Your Year-End Audit Checklist
Audits happen after the policy period closes, so the end of the year is a good time to get organized. Before your next audit, pull together:
-
Payroll reports by employee for the full policy period, matching what you filed on your quarterly tax returns.
-
Job duties for each employee, so payroll lands in the right class code. An office manager and a field tech are often rated very differently.
-
Certificates of insurance from every subcontractor, showing workers’ comp coverage in force for the dates they worked for you. Collect them before the job starts, not after the auditor asks.
-
A list of 1099 payments with what each person did for you, so you can explain who is truly independent.
-
Owner and officer status. Know whether you included or excluded yourself and any corporate officers on the policy, and make sure the audit reflects that choice.
-
Any mid-year changes: new locations, new services, layoffs, or seasonal staff.
Update the Estimate Before the Audit Does It for You
If your payroll has grown this year, tell your agent now. Updating your estimate mid-term can spread the cost over your remaining installments instead of landing as one lump sum after the audit. It also helps make sure you are buying enough coverage for the business you actually run today.
If your payroll dropped, that matters too. You may be paying deposit premium on payroll that no longer exists.
And if an audit result looks wrong, you do not have to just accept it. Classification and audit disputes in Massachusetts have a review process, and the documents on the checklist above are what you will need in those conversations.
The Bottom Line
The Lowell case is a reminder that underreported payroll eventually surfaces. For most Massachusetts business owners the stakes are smaller but still real: a surprise audit bill, a classification error, or a subcontractor without coverage who becomes your problem.
Want a second set of eyes before your next audit? Send Titan Insurance your current workers’ comp declarations page and your most recent audit, and we will review your class codes, payroll estimate, and subcontractor exposure with you.